Rate Pressure, Worker Classification, and Portfolio Reshaping Test Franchise Resilience
A fifth rate hike in 2026, a landmark High Court ruling on worker classification, and the near-collapse of a major retail chain paint a confronting picture for franchise networks navigating an increasingly unforgiving operating environment. Franchisors and franchisees alike must contend with tightening consumer spending, rising financing costs, and a legal landscape that is actively redefining workforce obligations. These developments demand immediate attention to cost structures, compliance frameworks, and long-term network planning.
- Fifth RBA rate hike this year takes cash rate to 4.85 per cent
- Uber loses $81 million High Court battle in blow for gig economy
- David Jones faces imminent administration after landlord negotiations collapse
- Fast food operators restructure brand portfolios as global market heads towards US$2.57 trillion by 2031
- NAB profit falls to $6.1 billion as overdue home loan repayments rise
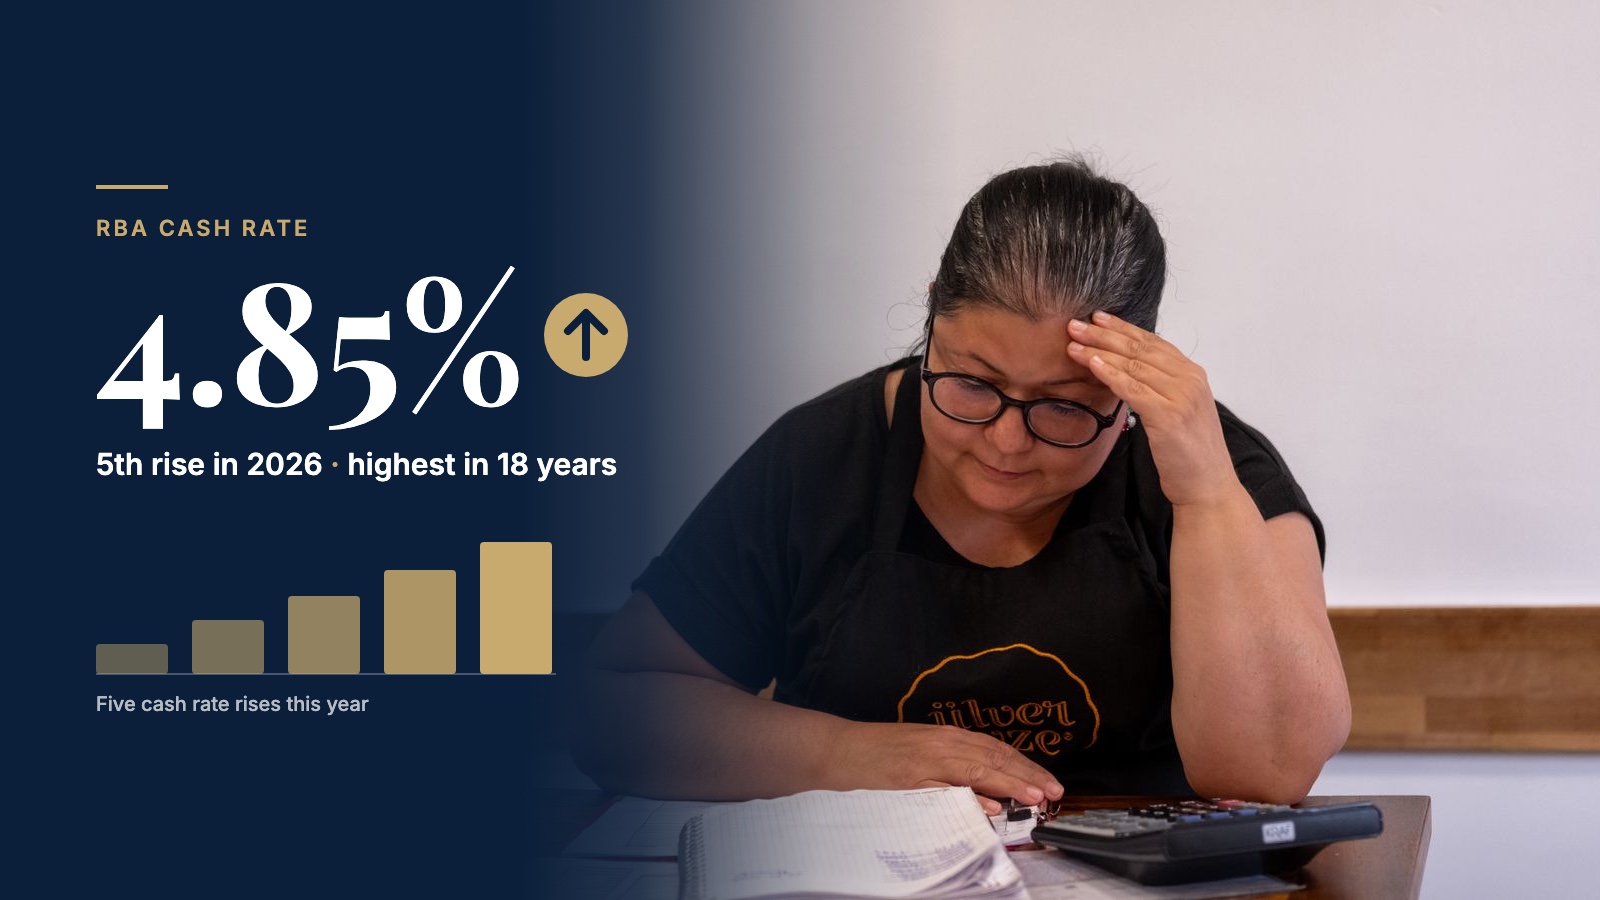
Fifth RBA rate hike this year takes cash rate to 4.85 per cent
The RBA has delivered its fifth rate increase of 2026, lifting the cash rate to 4.85 per cent, the highest level in 18 years.
Higher interest rates push up borrowing costs for franchisees carrying business loans, fit-out finance, or commercial property debt, putting real pressure on already thin margins. Franchisors should expect that prospective franchisees will face tougher lending conditions, which could slow network growth. Existing franchisees may need to renegotiate payment plans or seek fee relief under the Franchising Code’s good faith obligations as debt servicing costs climb.
Uber loses $81 million High Court battle in blow for gig economy
Uber has lost its High Court appeal in a landmark case, a result expected to carry broad implications for the gig economy and how workers are classified.
High Court rulings on worker classification can reshape how franchise networks structure their relationships with drivers, couriers, and other operatives. If gig workers are more readily treated as employees, franchise systems built on contractor models face higher wage, superannuation, and insurance obligations. Franchisors should review their operational models and disclosure documents to make sure they comply with any broadened definition of employment.
David Jones faces imminent administration after landlord negotiations collapse
The 188-year-old department store chain could appoint administrators by Thursday after failing to reach agreement with landlords, with up to half its stores at risk of closure.
A major retailer entering administration can trigger lease co-tenancy clauses that affect franchised tenants in the same shopping centres, potentially giving them grounds to renegotiate rent or exit their lease. Franchise systems with concessions or stores inside or near David Jones locations should review their lease terms for these provisions. The collapse also points to broader retail distress that franchisors need to factor into site selection and network planning.
Fast food operators restructure brand portfolios as global market heads towards US$2.57 trillion by 2031
Global fast food operators are reshaping brand portfolios, pricing strategies, and capital allocation as competitive pressure intensifies.
Portfolio restructuring by major QSR franchisors can lead to brand disposals, refranchising, or changes to franchise fee structures that directly affect Australian master franchisees and individual operators. Franchisees should watch whether their franchisor’s global strategy could result in brand repositioning or altered supply chain arrangements. Under the Franchising Code, material changes to the franchise system must be disclosed, so operators should make sure they are receiving timely updates.
NAB profit falls to $6.1 billion as overdue home loan repayments rise
Australia’s biggest business lender has reported falling profit and rising home loan arrears, noting that household savings buffers remain in place but are weakening.
NAB is a major lender to small and medium businesses, including franchise operators, so rising arrears and tighter credit conditions may see the bank impose stricter lending criteria on franchise borrowers. This affects both new entrants trying to secure finance and existing franchisees looking to refinance. Franchisors who rely on NAB panel accreditation or referral arrangements should prepare for longer approval timeframes and potentially reduced loan to value ratios for incoming franchisees.
Key Takeaways
- The RBA’s cash rate increase to 4.85 per cent, combined with NAB’s report of rising home loan arrears and weakening household savings buffers, signals sustained pressure on consumer discretionary spending across franchise networks.
- Uber’s High Court loss on worker classification will have far-reaching implications for franchise systems that rely on contractor or gig-style labour arrangements, making it critical to review engagement models against the evolving legal standard.
- David Jones’s potential administration after failed landlord negotiations is a stark reminder that franchise tenants should stress-test their own lease arrangements and ensure they have adequate protections before financial distress limits negotiating leverage.
- Global fast food operators restructuring brand portfolios and pricing strategies reflects a competitive recalibration that Australian franchise systems should monitor closely when planning capital expenditure and brand development.
- Franchisors should be proactively engaging with franchisees on cash flow management and compliance readiness, as the convergence of higher borrowing costs, changing employment law obligations, and weakening consumer confidence creates compounding risk across the sector.
Minerva Law has acted for franchisors and franchisees across the full franchise lifecycle since 2013. Its Principal, Tsungai Mukushi, has practised as a franchise lawyer since 2008.
minervalaw.com.au