Insurance Law
When the policy is tested
Coverage advice, disputed claims and policy reviews for business owners and directors, and claims, coverage and recovery work for insurers and underwriters. Both sides of the policy, read by lawyers who know how each side thinks.
What we do
Insurance work, by side
Most people meet insurance law twice: when they take the policy out, and when a claim is refused. Insurers and underwriters meet it every day. We act on both sides, which is the point: a policyholder’s claim is argued by lawyers who know how an insurer assesses it, and an insurer’s position is advised on by lawyers who know how a policyholder will attack it.
Policyholders
Is it covered?
Policies reviewed before you need them, and claims pressed properly when you do.
Disputed claims
When a claim is denied
The insurer’s reasons tested against the policy and the Insurance Contracts Act, and the complaint or claim run where the answer is wrong.
Insurers and underwriters
Coverage, defence and recovery
Coverage opinions, claims defence and subrogated recoveries, handled commercially.
01
Policy review and coverage advice
Before the loss, not after it
A policy is a contract, and most business owners sign it without reading the exclusions. We review public liability, professional indemnity, directors and officers, business interruption, cyber and industrial special risks policies before they are placed or renewed, and tell you in plain terms what is covered, what is not, and what your disclosure obligations are so the cover is still there when it is needed.
- Policy reviews before placement and renewal
- Duty of disclosure and misrepresentation
- Exclusions, conditions and sub-limits explained
- Contractual insurance obligations in leases, franchise agreements and supply contracts
02
Denied and disputed claims
Testing the insurer's reasons
An insurer that denies a claim must give reasons, and the reasons have to hold up against the policy wording, the Insurance Contracts Act and the General Insurance Code of Practice. We review the denial, press the insurer through its internal dispute process, take the matter to the Australian Financial Complaints Authority where it fits, and litigate where it does not. Business interruption, property damage, liability and professional indemnity claims are the ones we see most.
03
Directors, professionals and the claims against them
D&O and professional indemnity
A claim against a director or a professional is two problems at once: the claim itself, and whether the insurer will fund the defence. We notify the insurer correctly and in time, manage the reservation of rights, advise on the conduct of the defence, and deal with the insurer where it disputes cover. Where the claim is a regulatory investigation, the same discipline applies.
- Notification and reservation of rights
- Defence costs and conduct of the defence
- Coverage disputes with the insurer
- Professional negligence and regulatory claims
04
For insurers and underwriters
Coverage opinions, claims defence and recoveries
We advise insurers and underwriting agencies on whether a claim falls within cover, defend liability and property claims brought against insureds, and run subrogated recoveries against the parties responsible for a loss. The advice is commercial: whether to indemnify, settle or defend, decided early and on the numbers.
05
Insurance in a franchise system
Mandated cover, certificates and the gaps between them
Franchise agreements require franchisees to hold specified cover and name the franchisor as an interested party. The gaps appear when the cover lapses, the limits are wrong, or a claim falls between the franchisor’s policy and the franchisee’s. We draft and review the insurance clauses, advise on who is covered for what, and act when a claim exposes the gap.
How we work
Three steps
01
Send the policy and the correspondence
The policy schedule, the wording, the claim and the insurer’s letters. We tell you where the claim stands and what it will cost to pursue or defend.
02
A plan with an agreed scope
A written scope and a quoted fee for each stage, from the internal dispute process through to AFCA or court.
03
The right forum, used properly
Internal review, AFCA, negotiation or court, chosen on what the claim is worth and how fast it needs to resolve.
Who you will work with
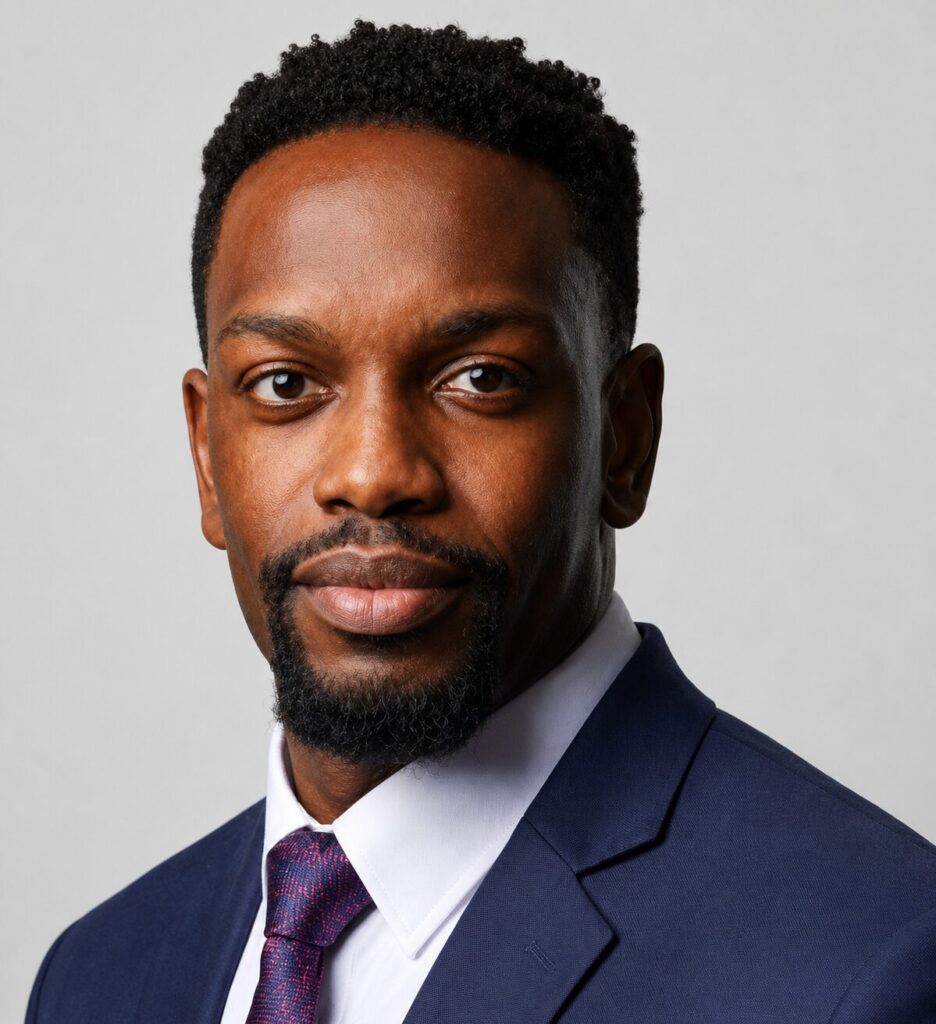
Principal
Tsungai Mukushi
Principal of the firm, admitted in 2008 and a franchise and commercial lawyer since. Tsungai has established 63 franchise systems, acted on 399 business sales and acquisitions and resolved 162 disputes at mediation, and he owns and runs businesses of his own, so the advice starts with what the decision means commercially.
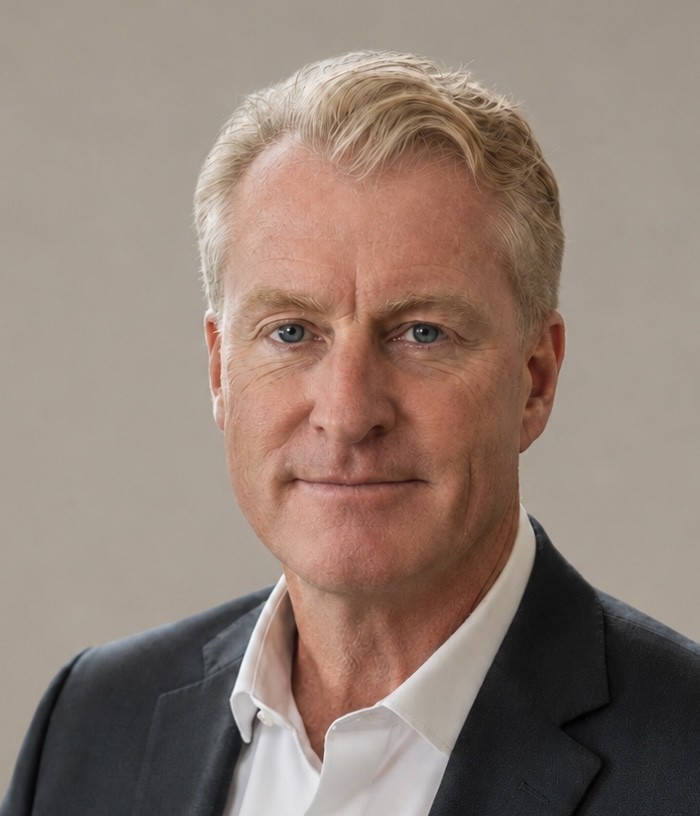
Consultant Lawyer
Damian Bourke
A lawyer, nationally accredited mediator and family dispute resolution practitioner, with thirty years in property development and finance and earlier work as a building surveyor and inspector. Damian has sat on the client’s side of complex deals and brings both commercial judgment and steadiness to a hard matter.
Legal Consultant
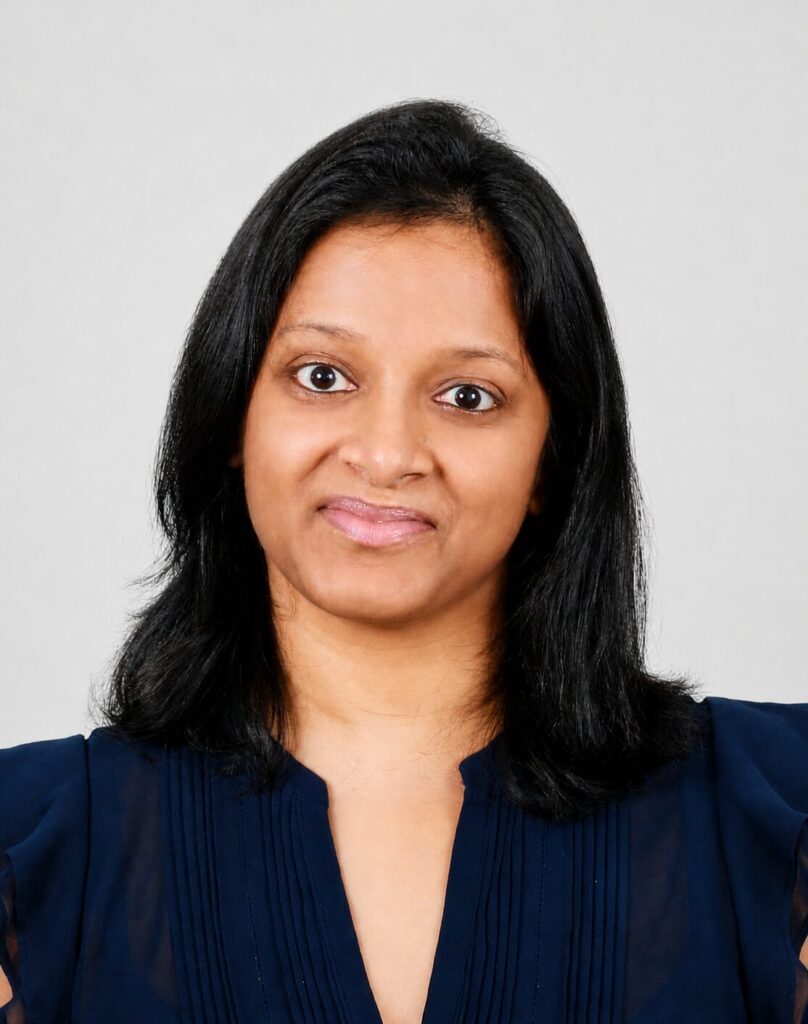
Ishani Perera
Extensive experience on complex corporate and commercial matters, drafting, reviewing and negotiating a wide range of commercial agreements. Ishani is pragmatic and detail-focused, and keeps matters moving so clients get a responsive, commercially sound result.
Client feedback
Voices of excellence
Live rating and reviews from the firm’s Google Business Profile.
Common questions
Insurance questions, answered
My insurer has denied my claim. What can I do?
Ask for the reasons in writing, then have the denial tested against the policy and the Insurance Contracts Act. Many denials rely on an exclusion or a non-disclosure argument that does not survive a close read. The next step is the insurer’s internal dispute process, then AFCA for most small business and consumer policies, then court.
What is AFCA and can my business use it?
The Australian Financial Complaints Authority is a free external dispute resolution scheme for complaints against insurers. Small businesses can use it within monetary limits, and the insurer is bound by its determination while the complainant is not. For larger claims, court is the forum.
Does the insurer have to pay my defence costs?
It depends on the policy and whether the claim falls within cover. Most liability, D&O and professional indemnity policies fund defence costs, often within the limit of indemnity, and often under a reservation of rights. How the claim is notified and managed affects whether that funding continues.
Do you act for insurers as well?
Yes. We advise insurers and underwriting agencies on coverage, defend claims against insureds and run recoveries. We run conflict checks before taking on any matter so that we never act against a client of the firm.
Also relevant
Related services
Litigation & disputes
Commercial disputes run at the lowest cost that still protects your position.
Related reading
Insurance reading
Articles and briefings from the firm on this area. Plain English, no lecture.
Next step
A policy to check, or a claim that has been refused?
Send us the policy and the correspondence and we will tell you where it stands, and what it costs to take further.